Referral losses and a planned sign-in shift raise questions that a strong reported quarter cannot answer.
Reddit reported the sort of revenue growth most established businesses would happily borrow: 53% in the third quarter. It was profitable, its global audience was larger than a year earlier, and it was earning more revenue for each active unique.
The October 30, 2026 selloff focused attention on a different part of the story. Search referrals were weakening, the U.S. daily audience had slipped, and management warned that continuing traffic trends could produce a further decline. Reddit was also preparing to test a more demanding entrance to the platform: signing in.
The tension is between the business Reddit has built and the way people find it. Better monetization can support a strong quarter even as a source of future visits becomes less dependable. The question is whether Reddit can keep people returning directly, at an attractive cost, while changing how they enter.
Why strong earnings did not settle the traffic question
Reddit’s official results showed third-quarter revenue of $895 million and net income of about $283 million. Global daily active uniques, or DAUq, rose 12% to 130.3 million. U.S. DAUq fell 2% to 50.7 million.
Those figures describe different things. Revenue measures commercial activity over the quarter. DAUq is Reddit’s measure of average daily active uniques, rather than a census of distinct people. Geography matters too: growth in the worldwide total does not establish growth in every important market.
A strong financial result can therefore coexist with a weaker audience signal. That does not make either number misleading. It makes the relationship between them worth understanding.
For a reader trying to explain the stock reaction, the useful distinction is timing. The reported quarter demonstrates what Reddit monetized. A warning about weakening referrals raises questions about the audience it can reach and retain next.
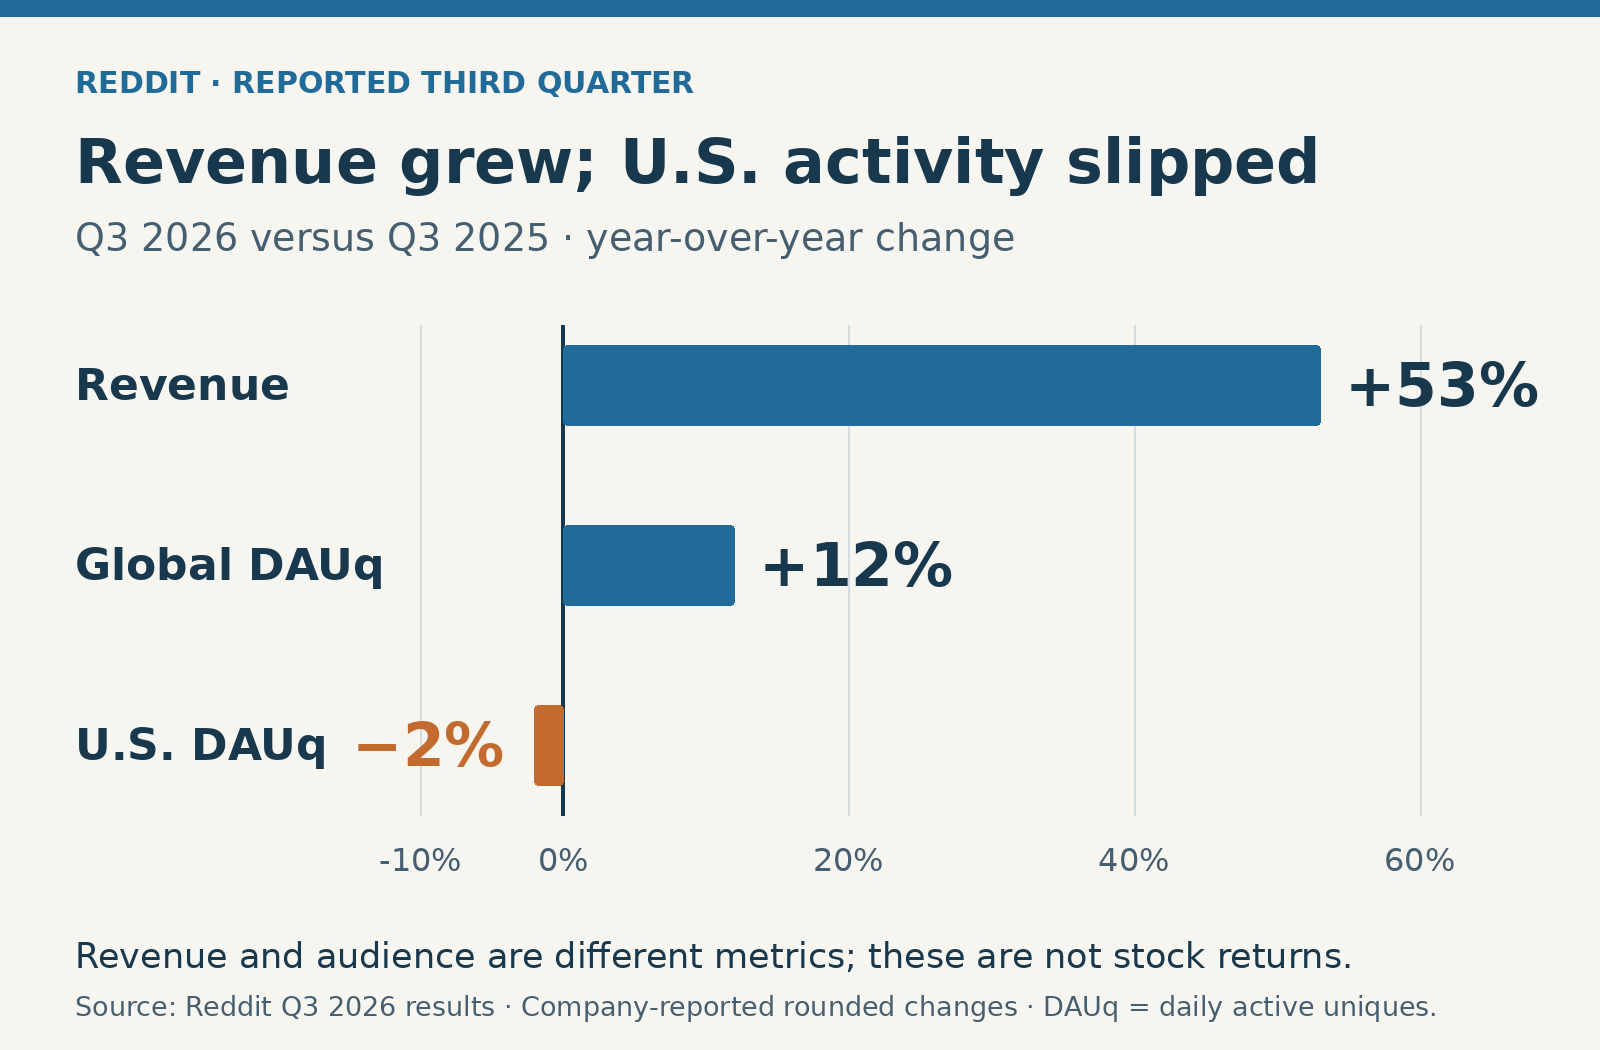
Reddit’s reported third-quarter 2026 changes versus the same quarter of 2025. Revenue and audience are different metrics; the bars do not measure stock returns.
Reddit reported third-quarter revenue growth of 53%, global daily-active-unique growth of 12% and a 2% decline in U.S. daily active uniques, all year over year. The comparison shows stronger revenue growth alongside uneven audience growth, rather than an equal relationship between traffic and sales.
Google traffic is also a return route
In its shareholder letter, Reddit said search referrals declined meaningfully in the third quarter, with the decline accelerating later. The effects mainly reached logged-out and web traffic, but also affected logged-in and app traffic because search helps reengage existing users.
That last detail matters. It is easy to imagine search as a conveyor belt carrying strangers to a site for the first time. It can also remind someone who already knows the service to return. Familiarity with a platform does not mean every visit starts from its home screen.
That creates two related growth tasks: attracting people and making the service a habit. A platform can perform well at one without solving the other. The commercial value of a community depends partly on how reliably it can bring its members back into a useful experience.
Reuters reported management’s explanation that Google’s AI search features were reducing referrals. That is an attributed company explanation. It does not independently establish how much of the change came from each Google feature or rule out every other influence.
The immediate business issue is clearer than the full causal argument: a discovery channel Reddit used was sending less traffic, and the company needed to respond.
The audience warning has a condition attached
Management said that, if the recent rate of decline continued, fourth-quarter DAUq could fall by a low-double-digit percentage from its current roughly 130 million base.
That is a conditional outlook. It should not become an inevitable result, an exact percentage forecast or a year-over-year decline with a different baseline. A referral is also not automatically a unique person. Counting visits and counting an audience are related measurement problems, with different definitions.
The condition matters because Reddit’s own response can affect the eventual outcome. Product changes, retention and user acquisition are part of the business being evaluated. A warning identifies a risk under continuing trends; subsequent results will show how those trends and responses developed.
Better monetization is a substantial countercase
Reddit reported global average revenue per unique, or ARPU, of $6.87, up 36% from $5.04 a year earlier. The measure divides quarterly revenue by average DAUq. Higher monetization alongside a larger global audience helps explain the reported revenue growth.
The arithmetic also sets a limit on the interpretation. ARPU and revenue share a numerator, so they are not independent proof of two separate business improvements. ARPU can reflect several things; it is not a clean measure of ad-price increases alone.
Still, the commercial distinction is useful. Losing a visit does not automatically mean losing the same percentage of revenue. Some activity is more valuable to advertisers, more engaged or easier to monetize than other activity. The mix of what remains matters.
Reddit said logged-in and app audiences grew sequentially and supplied over 80% of monetization. Those categories overlap. Their combined importance supports a real countercase to a simple story of collapsing reach and collapsing revenue moving in lockstep.
The same countercase has a boundary: these valuable audiences can also return through search. Strong monetization gives Reddit something valuable to defend. It does not make the discovery problem disappear.
Why Reddit wants more people to sign in
Reddit planned fourth-quarter tests of a primarily logged-in experience in selected markets outside the United States, with the results informing a broader version. That describes a test and a proposed direction, rather than a completed worldwide restriction.
There is a recognizable business tradeoff. A signed-in relationship can help a service recognize preferences, personalize an experience and develop a repeat habit. Asking someone to sign in also adds a step between curiosity and participation.
For an occasional visitor who wants one answer, even a small obstacle can matter. For an existing member who values the community, it may be less important. Those are plausible differences in behavior, not measured outcomes of tests that have yet to establish their results.
Replacement traffic has a cost
Reddit said marketing and product improvements helped offset referral declines. That creates another question alongside audience size: what does it cost to bring people back?
Two businesses with the same audience and revenue can have different economics if one needs to spend much more to maintain that audience. The useful measures therefore extend beyond the number of visits. Retention, acquisition spending and the value of the resulting activity belong in the same assessment.
The current disclosures do not settle the full acquisition-cost or payback question. They support examining it. Strong revenue growth cannot, by itself, prove that replacement traffic will be cheap, durable or fully incremental.
Advertising generated $847 million of Reddit’s $895 million in quarterly revenue, about 94.6%. The $48 million Other category should not automatically be labeled entirely AI-licensing revenue. Reddit’s ability to sustain a valuable advertising audience remains central to the reported business.
What would make the next results reassuring?
The reproduced issuer shareholder letter gives fourth-quarter guidance of $1.000 billion–$1.030 billion in revenue and $480 million–$510 million in adjusted EBITDA. Those are management estimates, not completed results or a guarantee that the transition will be smooth.
The next useful evidence will connect audience quality with cost. Stable or improving logged-in and app activity would help. Revenue performance would show what that activity produced commercially. Acquisition and retention evidence would help explain how much effort was needed to sustain it.
The sign-in tests deserve the same treatment: judge their results rather than the appeal of the strategy alone. More direct visits and a stronger community habit would be valuable because they could make the route back to Reddit more dependable.
A stock-price recovery is a separate question from those operating improvements. The business has reported substantial strengths and a real distribution risk. The decisive development will be whether Reddit can turn the people who occasionally arrive for an answer into people who choose to come back.